Calculator
Dollar cost averaging calculator
Enter the amount you invest each time and the price on each purchase date. The calculator shows how many units you bought and your average cost per unit, next to the simple average of the prices.
Quick answer
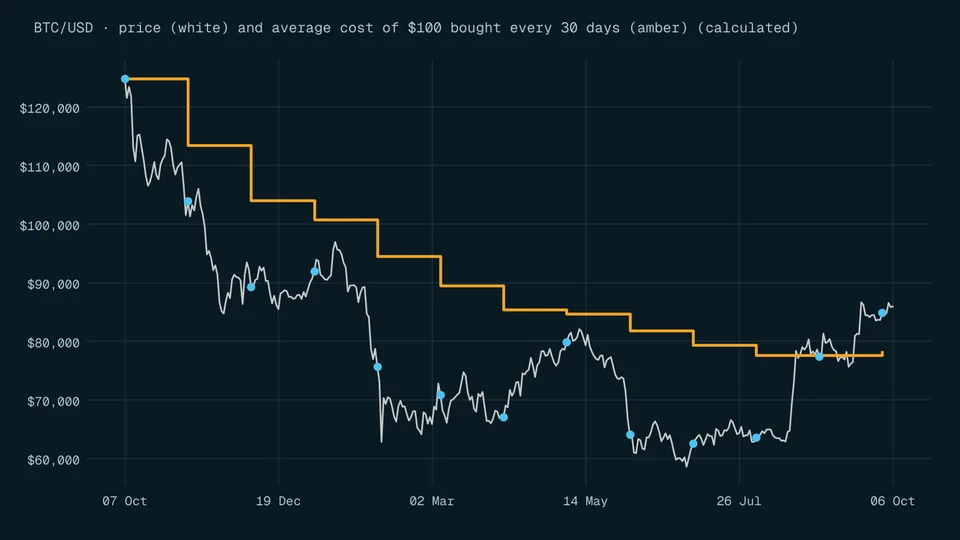
Dollar cost averaging means investing equal amounts at regular intervals regardless of the market [1]. Buying $100 at prices of 100, 80, 50, 80 and 100 gets 6.5 units for $500, an average cost of $76.92 (calculated). DCA does not prevent losses if prices keep falling.
This calculator needs JavaScript. The formula and a worked example below show the same calculation by hand.
Key points
- A fixed amount buys more units when the price is low and fewer when it is high [1].
- Your average cost is total invested / total units, which is usually below the simple average of the prices (calculated).
- FINRA notes DCA has lower risk but often lower returns than investing all at once, and more purchases can mean more fees [2].
On this page
How does the calculator work?#
Investor.gov, the US Securities and Exchange Commission's site for investors, defines dollar-cost averaging as investing your money in equal portions, at regular intervals, regardless of the ups and downs in the market [1]. The calculator follows that definition. For each purchase it divides your fixed amount by that day's price to get the units bought, adds up the units, then divides the total invested by the total units.
units bought each time = amount / price on that date
average cost = (amount × number of purchases) / total units
It also shows the simple average of the prices you entered, so you can see the difference. Because a fixed amount buys more units when the price is low and fewer when it is high [1], the cheap purchases carry more weight. That is why your average cost usually ends up below the simple average of the prices, and equals it only when every price is the same (calculated).
Can you check the result by hand?#
| Purchase | Price | Amount | Units bought |
|---|---|---|---|
| Purchase 1 | $100 | $100 | 1.00 |
| Purchase 2 | $80 | $100 | 1.25 |
| Purchase 3 | $50 | $100 | 2.00 |
| Purchase 4 | $80 | $100 | 1.25 |
| Purchase 5 | $100 | $100 | 1.00 |
| Total | $76.92 average cost | $500 | 6.50 |
The default inputs, purchase by purchase. All figures calculated.
Does dollar cost averaging beat investing all at once?#
Not reliably. The Financial Industry Regulatory Authority (FINRA) says spreading investments out has lower risk but often produces lower returns than lump sum investing, especially over longer periods, partly because part of your money stays in cash and can miss gains [2]. FINRA also says DCA can help limit losses in significant market declines [2]. The table shows both sides with $500 in total, invested either as five $100 purchases or all at the first price.
| Price path | DCA: value at the last price | All at once: value at the last price |
|---|---|---|
| Falling: 100, 90, 80, 70, 60 | $387.38 (down 22.5%) | $300.00 (down 40%) |
| Dip and recover: 100, 80, 50, 80, 100 | $650.00 (up 30%) | $500.00 (no change) |
| Rising: 50, 60, 80, 100, 120 | $810.00 (up 62%) | $1,200.00 (up 140%) |
$500 in total, before fees. All figures calculated. Made-up prices to show the arithmetic, not a forecast for any asset.
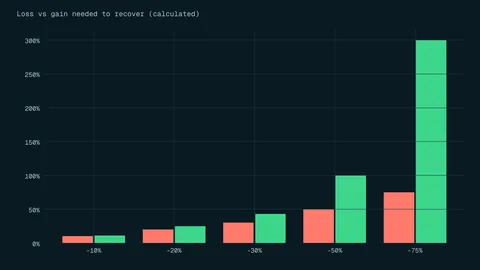
In the falling path, DCA still lost money; it lost less than buying everything at the start. In the rising path, buying everything at the start did better. No schedule removes the risk of the asset itself. To see how hard it is to climb back from a fall like the first row, try the drawdown recovery calculator.
What does the calculator not account for?#
- Fees. FINRA notes that DCA can mean higher fees than a lump sum because of the greater number of transactions [2]. A $2 fee on each of five $100 purchases costs $10, or 2% of the $500, against $2 for one purchase (calculated). Check real costs with the trading cost calculator.
- Where prices go next. The result depends entirely on the prices you type in. The calculator does not predict them.
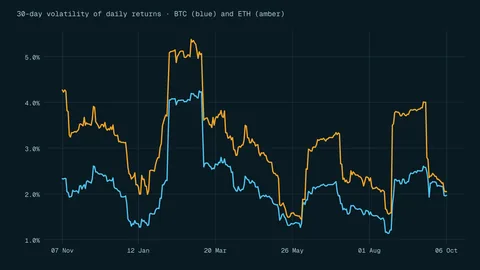
- Crypto risk. Neither FINRA's article nor the Investor.gov definition is about crypto. The SEC describes bitcoin and ether as highly speculative and volatile [3], and the UK FCA says to be prepared to lose all the money you put into crypto [4]. A regular schedule does not change that; read why crypto is so volatile.
- Taxes and timing. Tax treatment and the exact time of each purchase are outside the calculation.
Frequently asked questions#
Does dollar cost averaging guarantee a profit?
No. If the price ends below your average cost, you have a loss. In the falling example above, $500 invested in five steps was worth $387.38 at the last price (calculated). FINRA presents DCA as a way to manage risk with trade-offs, not as a way to avoid losses [2].
Why is my average cost lower than the average price?
Because a fixed amount buys more units at low prices [1], so those purchases count more in your average. With the default inputs, the average cost is $76.92 and the simple average price is $82.00 (calculated).
Why does DCA help some people stick to a plan?
FINRA says a disciplined schedule can remove some of the emotion from investing and might help you avoid impulsive decisions [2]. That matters most when prices swing; read about FOMO and herding to see why.
The bottom line#
Use the calculator to see what a regular, fixed purchase does to your average cost, then check the same prices against a single purchase and against fees. DCA spreads out when you buy; it does not reduce the risk of what you buy. Read the risk disclosure and the crypto basics guides before putting money into crypto.
Sources
Education only. This page is not investment, tax or legal advice. Trading and crypto can lose you money. See our risk disclosure.